By Peace Udugba
The Organized Private Sector of Nigeria (OPSN) has opposed the National Pension Commission’s (PenCom) proposed increase in mandatory pension contributions, warning that the move could trigger job losses, weaken businesses and undermine Nigeria’s economic recovery.
In a joint statement issued by the umbrella body, which comprises the Manufacturers Association of Nigeria (MAN), the National Association of Chambers of Commerce, Industry, Mines and Agriculture (NACCIMA), the Nigeria Employers’ Consultative Association (NECA), the Nigerian Association of Small and Medium Enterprises (NASME), the Nigerian Association of Small Scale Industrialists (NASSI), and 25 other sectoral employer associations, the OPSN described the proposal as a “Greek gift” to Nigerian workers.
According to the group, while the proposal is being presented as a means of improving workers’ retirement benefits, it could ultimately increase the cost of doing business, reduce employment opportunities, suppress wage growth and heighten compliance challenges for employers.
The OPSN noted that under the Pension Reform Act 2014, employers currently contribute 10 per cent while employees contribute eight per cent, bringing the total mandatory pension contribution to 18 per cent of monthly emoluments. It argued that this is comparable to the Organisation for Economic Co-operation and Development (OECD) average mandatory pension contribution rate of 18.8 per cent.
The group insisted that any proposal to increase the contribution rate must be backed by credible actuarial evidence specific to Nigeria, demonstrating that the current rate is inadequate and that a higher contribution would not negatively affect employment, wages, business sustainability or compliance.
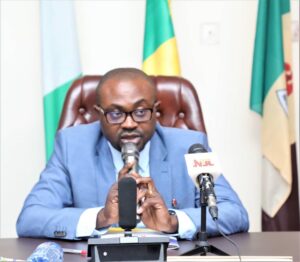
Speaking on behalf of the group in Lagos, NECA Director-General, Mr. Adewale-Smatt Oyerinde, faulted the process leading to the proposal, saying announcing a planned increase while stakeholder consultations are still ongoing undermines meaningful engagement.
He stressed that previous adjustments to pension contribution rates followed extensive consultations involving government, employers, organised labour and other stakeholders, adding that any future review should emerge from transparent social dialogue supported by actuarial, economic and employment impact assessments.
The Director-General of MAN, Mr. Segun Ajayi-Kadir, warned that businesses are already grappling with high energy costs, rising interest rates, exchange-rate volatility, weak consumer demand and multiple regulatory obligations.
According to him, imposing another statutory payroll cost without adequate impact assessment could force businesses to slow recruitment, delay wage increases, reduce workforce size, suspend expansion plans or transfer additional costs to consumers through higher prices.
He added that although employees may directly contribute more under the proposal, they could also suffer indirect consequences through slower wage growth, fewer employment opportunities, job losses and increased cost of living.
Similarly, NACCIMA Director-General, Mr. Sola Obadimu, argued that the proposal contradicts ongoing government efforts to improve the business environment and stimulate economic recovery.
He maintained that imposing additional financial obligations on employers at a time businesses are struggling with economic challenges could undermine the benefits of broader fiscal reforms.
Obadimu emphasised that reforms should be assessed not only on their intended benefits but also on their cumulative impact on employment, investment, inflation, wages and business survival.
The Director-General of NASSI, Engr. Ifeanyi Oputa, warned that micro, small and medium-sized enterprises (MSMEs) would bear the greatest burden if employer pension contributions are increased.
He noted that many MSMEs already operate on thin profit margins while contending with rising operating costs, multiple taxes and limited access to affordable financing.
According to him, imposing additional statutory obligations could discourage businesses from hiring workers formally and push more enterprises into the informal sector, thereby weakening rather than strengthening the pension system.
The OPSN called on the Federal Government and PenCom to prioritise inflation control, business sustainability and job creation instead of introducing policies that further reduce workers’ purchasing power.
The group also urged the government to undertake a comprehensive economic and employment impact assessment before considering any adjustment to pension contribution rates.
It further called for genuine and transparent consultations involving all stakeholders and insisted that no increase should be implemented until Nigeria achieves greater macroeconomic stability.
The OPSN reiterated that it supports reforms aimed at improving retirement security but stressed that sustainable pension reforms must strike a balance between protecting workers’ future benefits and preserving existing jobs and businesses.
According to the group, a strong pension system can only thrive on the foundation of strong businesses, stable employment and a healthy economy, warning that any reform that increases the cost of employment without addressing prevailing economic challenges would ultimately become a “Greek gift” to Nigerian workers.